Skip to content
CrediSegur — home page
All toolsFree · 2 minutes · no personal data

Cada € Conta: Where Does Your Money Go Every Month?

Create your household budget and see how much you have left, where each euro goes, and where you can make changes. And before a purchase, find out how many hours of work it costs.
  • No account or registration
  • With annual expenses
  • Your numbers stay with you
What do you want to know

Three questions to find out how much you have left per month

Values per month. They can be approximate: what matters is the order of magnitude.
€

We use €2,200, a reference value.
€

We use €650, a reference value.
€

We use 60% of what comes into the house.
It's a quick calculation. In 'In detail' you separate the accounts and see where you can adjust.

How we calculate

You don't need to track every coffee. You need to know where most of the money goes.
  1. Gather the numbers

    Open your banking app and check the last 3 months. Use the averages, not the best month.
  2. Don't forget the year

    IMI, IUC, insurance, holidays, and Christmas don't appear every month, but they need to be paid. Divide by 12.
  3. Separate needs from wants

    Home, bills, and food are needs. Restaurants, leisure, and shopping are wants.
  4. Give a purpose to what's left

    First, an emergency fund. Then, your goals. Money without a purpose disappears.
For reference: on average, a family in Portugal spends €258 per month on groceries and €171 on restaurants and accommodation. These are averages for families of all sizes, not a target. Source (in Portuguese): INE, Inquérito às Despesas das Famílias 2022/2023 (resultados de junho de 2024).

Illustrative cases

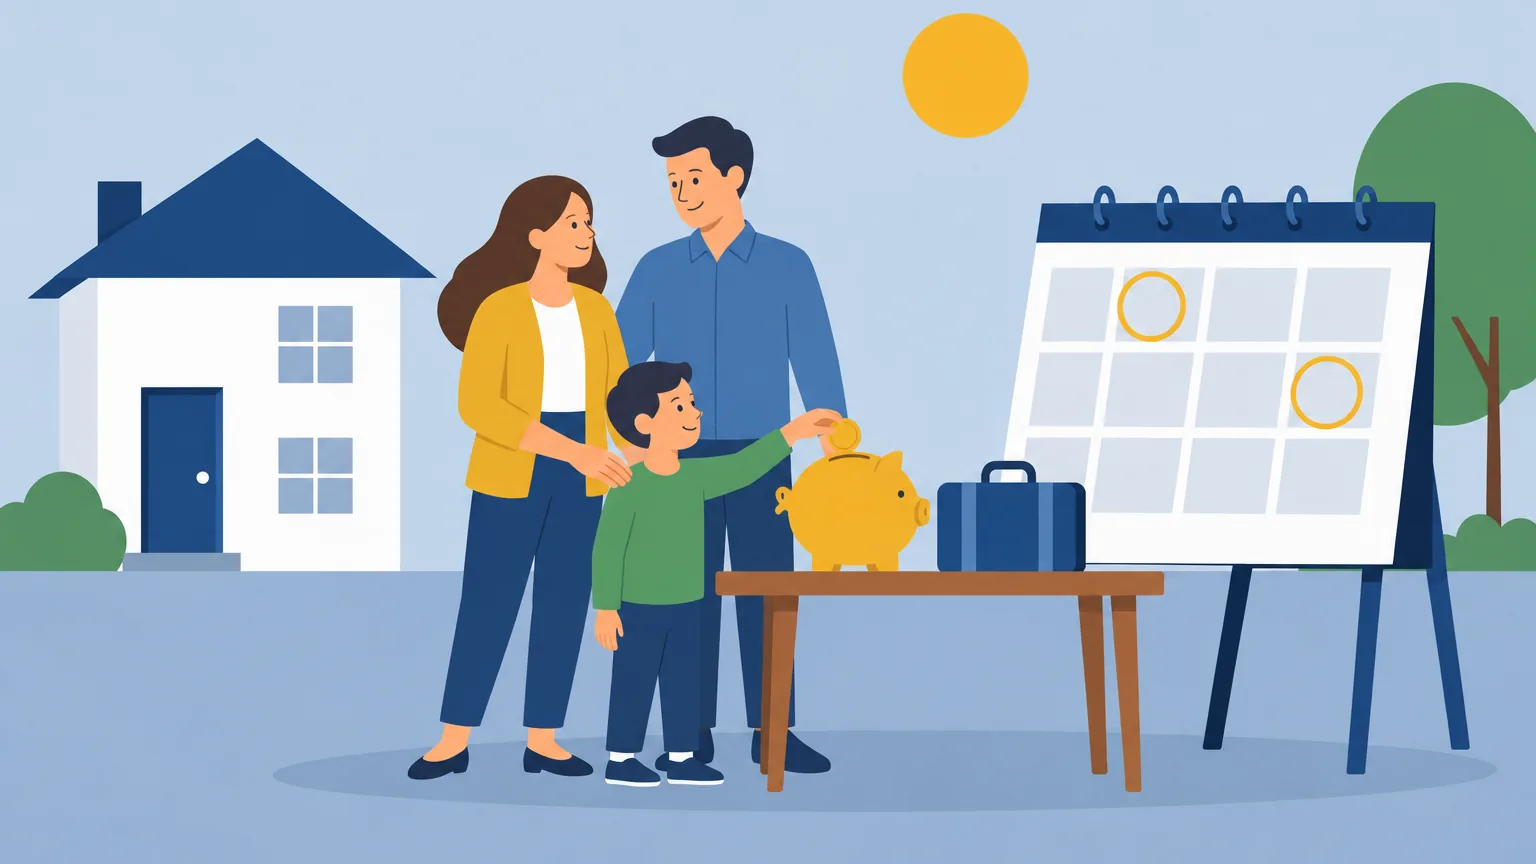
Illustration of Lara e Henrique with the child, in front of the house, with the annual expenses calendar
Illustrative example

Lara e Henrique thought the money was enough. The annual expenses were missing.

They live in Paredes with a child. They bring in €2,200 per month, and month by month, the accounts seemed to add up. But in August and December, they were always anxious.
  1. 1“If the accounts add up, why are there months when it doesn't?”
  2. 2The IMI, the IUC, vacations, and other annual expenses total €1,590: that's €133 per month. Without them, they had €117 left; with them, they are short €16 per month.
  3. 3They started setting aside €133 per month for annual expenses. And they saw where to adjust: with the tool's assumptions, they could free up about €75 per month.

Annual expenses €1,590

What's left per month, with everything−€16

What's left per month, with everything
−€16
they thought they had €117 left
Annual expenses
€1,590
€133 per month
Can free up
€75
per month, hypothetically
“The money didn't disappear. We just weren't accounting for the whole year.” — Lara
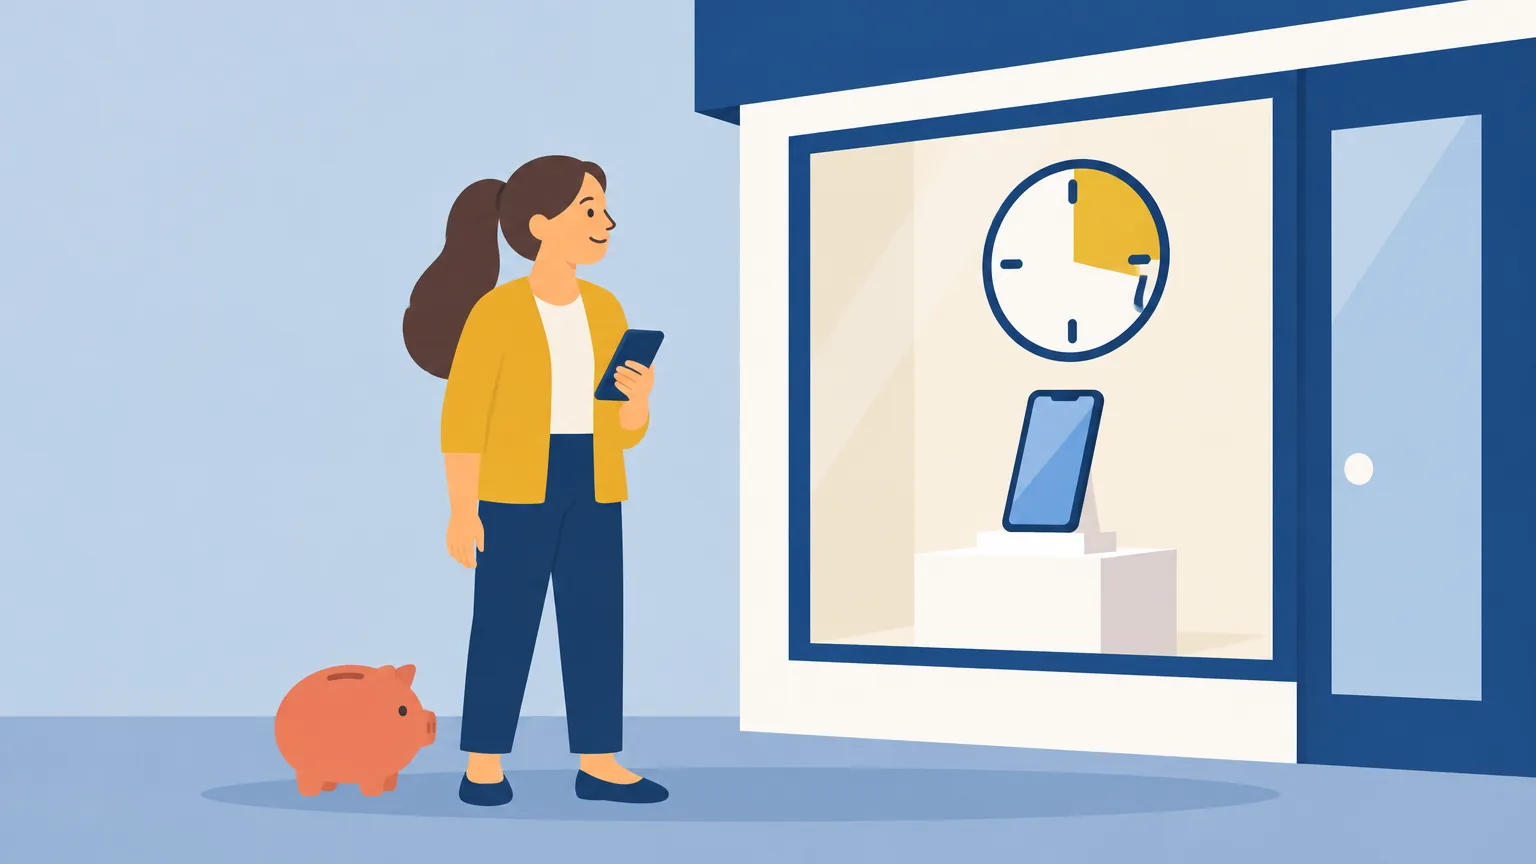
Illustration of Matilde looking at a new phone, with a clock beside
Illustrative example

Matilde wanted a new phone. She calculated it in work hours.

She is 27 years old, lives in Torres Vedras, and earns €1,050 per month. The phone cost €1,100, and the store proposed paying in 2 years. Hers still worked: it was a want, not a need.
  1. 1“It's just a few euros a month. What's the harm?”
  2. 2The phone cost 141 hours of work: 18 days. On credit, she would pay €50.24 per month and an additional €106 in interest. And the purchase would take 8 months of all she had left.
  3. 3She waited 3 days and chose a model costing €600: 77 hours of work. She saved the money in 5 months, without credit.

Interest not paid €106

Work hours saved64 hours

Work hours saved
64 hours
from 141 hours to 77 hours
Interest not paid
€106
rate as assumption
Saved in
5 months
without credit
“Almost a whole month working for a phone. No way.” — Matilde
*Illustrative, non-binding example, with values that are merely indicative and subject to confirmation. This does not constitute a credit offer and does not replace an assessment of each client’s personal and financial situation, nor the approval of the lending credit institution. CrediSegur (CRRF Brokerage, Lda.) — Tied Credit Intermediary registered with Banco de Portugal under no. 0001290. Possible savings are calculation assumptions, not proposals from any bank, insurer, or energy provider.

What's true and what's a myth in household budgeting

Four ideas we hear often, and what to do about each.
  • Myth«Budgeting is for those who earn little.»False. Those who earn more can also reach the end of the month without knowing where the money went. Budgeting is for choosing, not cutting.What to do: Do the quick calculation with three numbers and see how much you have left.
  • Truth«Small expenses add up a lot.»True. A coffee and a pastry every day add up to the price of a vacation by the end of the year. It's not about cutting them all: it's about seeing them.What to do: Put coffees, subscriptions, and small purchases in the «Day to day».
  • Myth«If the installment fits in the month, I can buy.»False. The installment fits, but you pay interest and have less flexibility for months. Several small installments make a big one.What to do: See the total cost and work hours in «Is it a want or a need?».
  • Depends«I should save 20% of what I earn.»It depends. It's the 50/30/20 rule, a good reference. But with an expensive house or young children, it might not be possible. Saving a little every month is worth more than a lot occasionally.What to do: Start with a fixed amount, on the day you get paid.

Frequently Asked Questions

No. The calculations are done on your phone or computer. They are only stored if you click on «Save on this device», and they stay there, not with CrediSegur. CrediSegur only receives your numbers if you request contact.
It's the list of what comes in and what goes out of the house every month. It helps you know how much you have left and decide where the money goes, instead of finding out at the end of the month.
Because they are the ones that catch families by surprise the most. IMI, IUC, annual insurance, vacations, and Christmas don't appear every month, but they are paid. We divide by 12 to know how much to set aside.
It's a rule of thumb: 50% of what comes in for necessities, 30% for wants, and 20% for savings. It's a reference for comparison, not an obligation. Many families spend more than half just on necessities.
We take your salary after deductions, multiply it by the salaries you receive per year, and divide it by the hours you work in a year. We account for 47 weeks of work, to discount vacations and holidays. This gives what you earn per hour. The price divided by that value is the work hours.
They are calculation hypotheses from CrediSegur for credit, insurance, and energy, the same as the fixed expenses simulator. They serve to give you an order of magnitude. They are not proposals: the exact value is only known with your bills. Telecommunications appear only as a tip: CrediSegur does not sell them.
Official data verified on 10/20/2026 · Sources: Diário da República, Autoridade Tributária, Banco de Portugal, INE, Segurança Social, Assembleia da República · see sourcesData from INE – Portugal, reused under the CC BY 4.0 licence.
Important note: Informative tool, calculated with the values you provide. It is not financial advice. Possible savings are calculation hypotheses with assumptions (Pressupostos CrediSegur para o orçamento familiar); they are not proposals or conditions from any bank, insurer, or energy provider. The interest rate (9.0%) and profitability (4.5%) are assumptions, not a credit proposal or guarantee. Consolidating credits into one can increase the total credit cost. CRRF – BROKERAGE, LDA (CrediSegur) is a tied credit intermediary registered with Banco de Portugal (no. 0001290) and an insurance agent registered with ASF (no. 421571530); it does not charge fees for credit intermediation. Credit granting is subject to the approval of the credit institution. Insurance proposals only after analyzing the client's needs.