IRS: 3 tax strategies few know that make all the difference
Did you simulate the IRS and the result was not as expected? Discover 3 tax strategies to start implementing now and see results in the 2026 IRS.The changes in withholding tables, updates to IRS brackets, and changes in the IRS Jovem regime allowed you, in 2025, to withhold less tax monthly and, consequently, increase liquidity in disposable income throughout the year, however, the bill has come due now!
But the truth is this: Your tax life is NOT just about validating invoices on the Finance Portal.
We have prepared three tax strategies for you to start implementing now and see results in the 2026 IRS:
I sold my house with capital gains. Now what?
If you made a profit from selling a property, you will need to declare those capital gains to the Tax Authorities. This can bring changes to your tax bracket and implications for tax calculation.
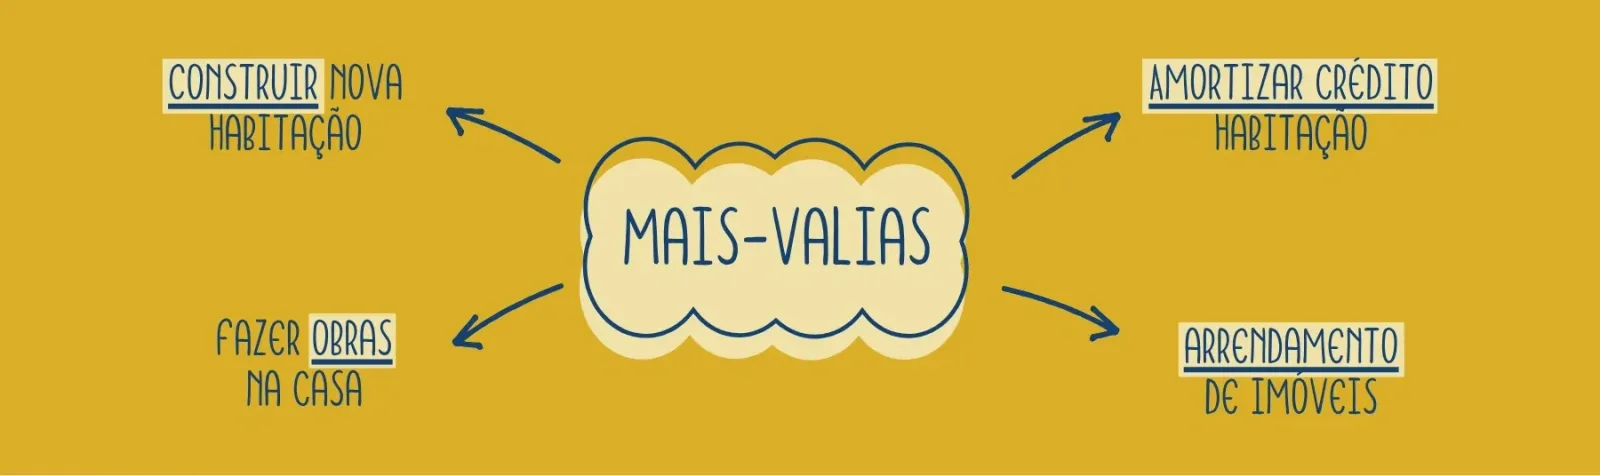
If you sold the house you lived in with capital gains (your own and permanent residence in the previous 12 months), the gain can be excluded from IRS if you reinvest the sale amount, minus the loan you paid off, in another own and permanent residence, in land to build it, or in expansion or improvement works, between 24 months before and 36 months after the sale, and declare this intention in annex G. For sales between 2026 and 2029, there is also an exclusion for reinvestment in rental properties, with limited rent and conditions for five years.
Want to know how much IRS you pay on your sale and how much it decreases if you reinvest? Simulate capital gains
PPR: the tax benefit many ignore
Let's start with the Retirement Savings Plan (PPR). What you apply there can give a tax deduction of 20%, up to 400 € (under 35 years), 350 € (35 to 50 years), or 300 € (over 50 years). The deduction only takes effect if you pay IRS and have not exhausted the global limit of deductions, it does not exist after retirement and is refunded, with an increase of 10% per year, if redeemed early outside the situations provided by law.
| Age | Deduction | Amount applied that exhausts the deduction | Maximum deduction |
|---|---|---|---|
| Under 35 years | 20% | 2000 € | 400 € |
| From 35 to 50 years | 20% | 1750 € | 350 € |
| Over 50 years | 20% | 1500 € | 300 € |
Health insurance also counts
Besides providing more security in accessing medical care, you can deduct in IRS 15% of the amount paid in health insurance, up to:
-
1000 € per household
-
500 € per person (individual taxation)
A family paying 1000 € per year in health insurance could recover about 150 € in IRS.
This article explains general IRS rules for 2026 and is not tax advice: for your specific case, talk to a certified accountant or consult the Tax Authority. If you want to know about the PPR (insurance) or health insurance, a CrediSegur credit manager will explain the products to you.
See you soon,
Carolina Francisco
Article by CrediSegur (CRRF – Brokerage, Lda.), a tied credit intermediary registered with Banco de Portugal under no. 0001290. We present proposals from the banks with whom we have a binding contract, identified in the Consumer Information, and we do not provide consulting services. Insurance agent registered with ASF under no. 421571530.