Joana and Diogo had €20,000 and two debts
In 25 years
With the plan€53,736
- Setúbal
- Home: €150,000 at 3.5%
- Personal Credit: €12,000 at 10.5%
- €20,000 set aside
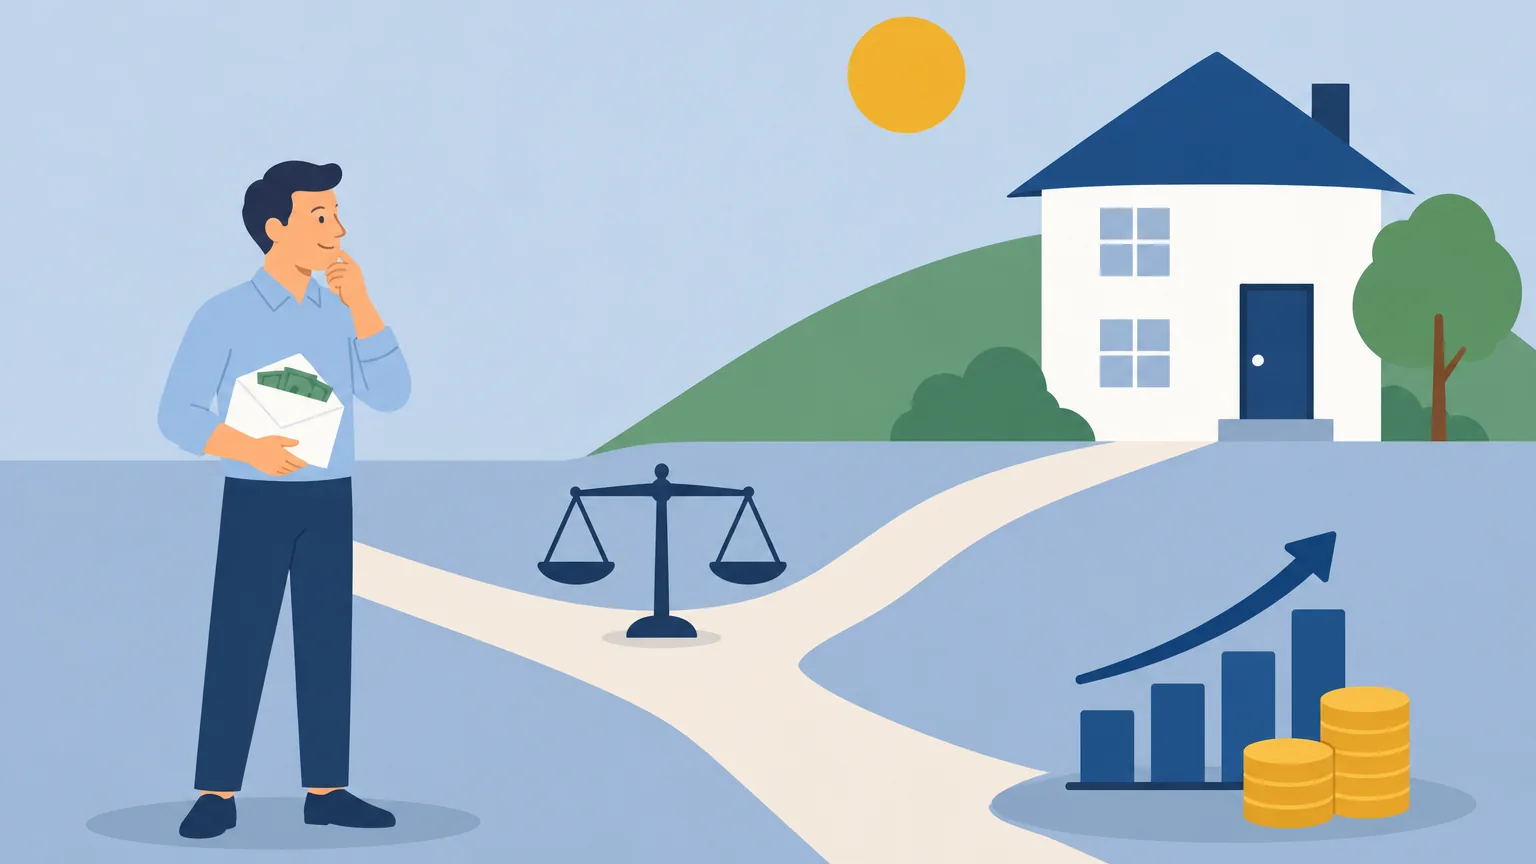
- 1. The dilemmaThey live in Setúbal. After years of saving, they put together €20,000. They owe €150,000 on the house, at 3.5%, and €12,000 on the car, a personal credit at 10.5%. Repay or invest?
- 2. Instinct: pay down the mortgage“It’s the biggest debt. It’s the one that weighs on us the most.”It makes sense. But the mortgage is the cheapest debt they have.They would end up with €47,361
- 3. The brother-in-law’s advice: invest it all“Idle money loses value. Put it all to work.”Better. But they keep paying 10.5% a year on the car while they hope to earn 4.5%.They would end up with €48,878
- 4. The math: separate good debt from bad“First the car, then we’ll see.”The car loan is bad debt: every euro they put there earns 10.5%, with no risk. The mortgage is good debt: low rate, asset that lasts. Plan: pay off the car and invest the rest.They end up with €53,736
The same €20,000. €6,375 more than following instinct and €4,857 more than investing it all, after 25 years.First you clear the bad debt. Then the break-even rate tells you whether it pays to repay the good debt or invest.